
How many credit cards should I have in the UK? It’s a common question, but there is no official ideal number. For some people, one well-managed credit card is enough. Others may benefit from having two or three for different purposes, such as everyday purchases, balance transfers or travel.
The important question is not how many cards you have, but whether you can manage them responsibly without building up unaffordable debt.
Whether you’re considering your first credit card or wondering if you already have too many, this guide explains how multiple credit cards affect your credit score, when having more than one makes sense and why fewer cards might be the smarter financial choice.
Quick Answer: How Many Credit Cards Should You Have?
The right number depends on your circumstances.
| Number of cards | Who might benefit? |
|---|---|
| 0 credit cards | People who do not need credit or prefer to avoid borrowing |
| 1 credit card | Anyone wanting a simple way to manage purchases and build a repayment history |
| 2 credit cards | People who can manage separate cards for specific purposes |
| 3 credit cards | Confident users who have a clear reason for each card |
| 4 or more | Experienced borrowers who can comfortably manage multiple accounts, balances and payments |
BudgetKin’s recommendation: Start with simplicity. If one card meets your needs, there is no reason to apply for more simply to increase the number you hold.
Having multiple credit cards is not automatically better for your credit score.
Is There a Recommended Number of Credit Cards in the UK?
No. There is no official UK rule stating that you should have one, two or three credit cards.
Credit reference agencies and lenders assess several factors when reviewing your credit history and applications.
These can include:
- Whether you make payments on time.
- How much of your available credit you use.
- Your existing debts and financial commitments.
- How frequently you apply for new credit.
- Your previous record of managing borrowing.
Someone with one credit card who consistently pays on time may appear less risky to a lender than someone with five cards and a history of missed payments.
The number of cards is only one part of the overall picture.
Is It Better to Have One Credit Card or Two?
For many UK households, one card is simpler to manage. However, a second credit card can offer genuine benefits in certain circumstances.
Benefits of having one credit card
One credit card means:
- One statement to check.
- One payment date to remember.
- Easier spending tracking.
- Less temptation to increase borrowing.
- A straightforward way to establish a responsible repayment history.
For someone starting to use credit, one card may provide everything they need.
Benefits of having two credit cards
A second card might make sense if it serves a different purpose.
For example, you could have:
Card 1: Everyday purchases
Used for planned spending that you can afford to repay.
Card 2: Balance transfers or travel
Used for a specific offer or feature that your existing card does not provide.
However, a second card also means another account to monitor.
If you regularly carry balances, struggle to meet repayments or find budgeting difficult, applying for another credit card might create more problems than it solves.
Using this approach fits well with the wider principles explained in Credit Cards and Debt Explained for UK Families, where structure and visibility are key.
How Many Credit Cards Can You Have in the UK?
There is no general legal maximum on the number of credit cards an adult can hold in the UK.
However, each lender decides whether to approve an application.
They may consider:
- Your income and regular expenditure.
- Your existing borrowing.
- Your credit history.
- Your affordability.
- Your recent credit applications.
- Their own lending policies.
Some providers also restrict how many credit cards you can hold with them.
Important: Being eligible for another credit card does not necessarily mean you should apply for one.
A larger total credit limit is not the same thing as having more money available to spend safely.
Does Having Multiple Credit Cards Improve Your Credit Score?
Not necessarily.
Having more credit cards does not automatically increase your credit score.
Responsible management of credit accounts can contribute positively to your credit history, but opening additional cards also creates risks.
What can help your credit profile?
- Making every payment on time.
- Keeping credit card balances manageable.
- Avoiding unnecessary applications.
- Staying within agreed credit limits.
- Maintaining a consistent record of responsible borrowing.
What can damage your credit profile?
- Missing repayments.
- Defaulting on accounts.
- Frequently approaching or exceeding credit limits.
- Making numerous applications in a short period.
- Taking on debt that becomes unaffordable.
Lenders also use their own affordability assessments and lending criteria. A high credit score does not guarantee approval.
According to Experian’s UK guidance on credit card numbers, responsible use matters more than simply increasing the number of cards you hold.
Credit Card Utilisation: Why It Matters
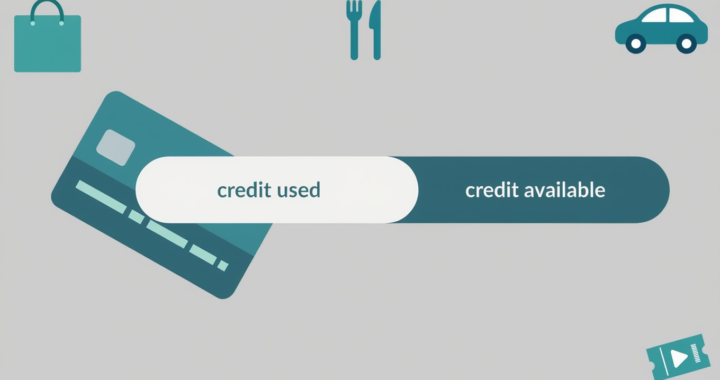
Credit utilisation is the proportion of your available credit limit that you are currently using.
It can influence how lenders and credit reference agencies assess your borrowing behaviour.
Example 1: One credit card
Imagine you have:
- Credit limit: £2,000
- Outstanding balance: £1,000
Your credit utilisation is:
£1,000 ÷ £2,000 × 100 = 50%
You are using half of your available credit.
Example 2: Two credit cards
Now imagine you have two cards:
- Card 1 limit: £2,000
- Card 2 limit: £2,000
- Total outstanding balance: £1,000
Your combined credit utilisation is:
£1,000 ÷ £4,000 × 100 = 25%
Your total utilisation is lower, even though the amount you owe remains exactly the same.
This illustrates why increasing available credit can affect utilisation.
However, opening a second card solely to lower utilisation is not always a good decision. The application may involve a hard credit search, and greater available credit could encourage additional spending.
It is often more useful to reduce outstanding balances than increase borrowing capacity.
Read our guide to credit card utilisation in the UK for more information.
How Many Credit Cards Are Too Many?
There is no magic number at which credit cards suddenly become a problem.
For one person, four cards might be manageable. For another, even one card could create financial pressure.
The warning signs matter more than the total number.
You may have too many credit cards if:
- You regularly forget payment dates.
- You struggle to remember what you owe.
- You make only minimum payments because you cannot afford more.
- You use one card to cover spending caused by another.
- Your balances keep increasing.
- You rely on credit cards for ordinary living costs.
- You feel anxious when statements arrive.
If these problems sound familiar, the priority should be controlling existing borrowing rather than opening additional accounts.
How Many Credit Cards Should a Family Have?
For families managing rent or mortgage payments, childcare, food, transport and household bills, simplicity can make a significant difference.
Consider a household using three cards:
- One for food and everyday spending.
- One for occasional purchases.
- One for a balance transfer.
This can work if the household has clear repayment plans and tracks every account.
But problems can develop if spending becomes fragmented across different cards and monthly statements.
A practical family budgeting example
Imagine a family has £600 available each month after essential bills.
They spend £400 on credit cards but only budget £250 for repayments.
Even if they have several cards and large combined limits, their borrowing may become increasingly difficult to manage.
The problem is not necessarily the number of cards. It is the gap between spending and affordable repayment.
BudgetKin tip: Include every credit card balance and planned repayment in your household budget. Never treat unused credit limits as savings or emergency funds.
Should You Close Credit Cards You No Longer Use?
Not always.
Closing an unused credit card can simplify your finances and reduce the temptation to borrow.
However, it can also reduce your total available credit, potentially increasing your utilisation percentage.
Example
Suppose you have:
- Card A: £2,000 limit and £500 balance.
- Card B: £3,000 limit and no balance.
Your combined utilisation is 10%.
If you close Card B, your utilisation rises to 25%, assuming your remaining balance and limit are unchanged.
That does not mean keeping unused cards open is always better.
Before closing an account, consider:
- Whether it charges an annual fee.
- Whether it encourages overspending.
- Whether you still need its benefits.
- Its effect on available credit.
- Whether you can monitor the account for suspicious activity.
The impact on your credit report also depends on the credit reference agency and how the account is reported. Closing an older card does not necessarily remove its payment history immediately.
For additional guidance, see Experian’s advice on unused credit cards.
Should You Apply for Several Credit Cards at Once?
Generally, making numerous credit applications in a short period is best avoided.
Formal applications can result in hard searches on your credit report.
Several recent hard searches may concern lenders, particularly if they suggest you are urgently seeking additional borrowing.
Before applying:
- Check your existing credit commitments.
- Consider whether a new card has a genuine purpose.
- Review the interest rate, fees and conditions.
- Use an eligibility checker where available.
- Make sure repayments fit your budget.
An eligibility check using a soft search generally does not affect your credit score, although you should confirm what type of check a provider uses.
For further information, read MoneyHelper’s guide to applying for credit.
What If You Already Have Credit Card Debt?
If you are carrying debt across multiple credit cards, adding another account is not necessarily the solution.
Start by understanding exactly what you owe.
For each credit card, write down:
- The outstanding balance.
- The interest rate.
- The minimum payment.
- The payment due date.
- Any promotional interest rate expiry date.
Prioritise essential household spending and make sure you understand which debts and bills need urgent attention.
If affordable, paying more than the minimum can reduce interest costs and help clear borrowing faster.
A balance transfer may reduce interest in some situations, but check transfer fees, promotional deadlines and what happens when the offer ends. Approval is not guaranteed, and transferring debt does not eliminate it.
If you are struggling to make repayments, free confidential debt advice is available from organisations such as StepChange and MoneyHelper.
You can also read our article on what happens when you only pay the minimum on a credit card.
The BudgetKin Three-Question Credit Card Test
Before applying for another credit card, ask yourself these three questions.
1. Does this card have a clear purpose?
Is it providing a feature you genuinely need, or are you applying simply because additional credit is available?
2. Can I comfortably manage the repayments?
Consider your existing bills, debts and irregular expenses.
Would another card create additional financial pressure?
3. Am I already managing my current cards well?
Check whether you consistently make payments on time and keep balances under control.
If the answer to any of these questions raises concerns, improving your current financial position may be more useful than applying for another card.
Frequently Asked Questions
How many credit cards should I have in the UK?
There is no official recommended number. One card can be sufficient, while two or three may be useful for different purposes. What matters most is responsible borrowing and affordable repayments.
Is it bad to have two credit cards?
No. Two credit cards are not automatically a problem. They may be useful when each has a clear purpose and both can be managed without increasing unaffordable debt.
Is three credit cards too many?
Not necessarily. Three cards may be manageable for someone who tracks spending, pays on time and understands the costs of borrowing. For someone struggling with debt, three cards could be too many.
Is four credit cards too many in the UK?
Four credit cards are not automatically excessive. The concern is whether you can manage all the accounts, monitor spending and afford repayments.
Can you have more than one credit card from the same bank?
Sometimes. Individual banks set their own rules about holding multiple cards, and some restrict which products existing customers can apply for.
Will having more credit cards improve my credit score?
Not automatically. Opening another card may change your available credit and utilisation, but it also creates a new account and may involve a hard credit search. Responsible repayment behaviour is more important than card count alone.
Should I have a credit card if I want a mortgage?
You do not need a particular number of credit cards to qualify for a mortgage. Lenders assess your credit history, affordability, income, debts and other circumstances. Avoid taking out credit unnecessarily just before applying for a mortgage.
Can I build a good credit history with just one credit card?
Yes. Making payments on time and managing a single card responsibly can help establish a positive borrowing history. Credit cards are not the only way to build credit history.
Should I cancel a credit card I never use?
It depends. Consider fees, temptation to overspend, account security and the possible effect on your available credit before making a decision.
What is more important than the number of credit cards?
Paying on time, managing debt, using credit responsibly and maintaining an affordable household budget are all more important than aiming for a particular card count.
Final Verdict: How Many Credit Cards Should You Have?
The best number of credit cards is the number you can manage confidently and affordably.
For some people, that means having no credit cards.
For others, one card is enough to cover everyday needs and establish a repayment history.
Two or three cards can offer flexibility, but only when each has a genuine purpose and the additional accounts do not encourage overspending.
There is no need to chase a particular number simply because someone suggests it is better for your credit score.
At BudgetKin, we believe that better financial decisions start with understanding your spending, controlling debt and building a budget that works for your household.
For a full overview of how card numbers, balances, and habits fit together, see Credit Cards and Debt Explained for UK Families.
Remember: More available credit does not mean more financial security.
Related BudgetKin Guides
If you want to make smarter decisions about borrowing and debt, explore these additional guides:
- Credit Card Utilisation Explained and Why It Matters in the UK
- Paying the Minimum on a Credit Card: What Really Happens in the UK
- Credit Card Mistakes That Hurt Your Finances
- Proven Debt Repayment Strategies to Crush Your Debt
This article provides general UK personal finance information and is not personalised financial advice. Credit scoring and lending decisions vary between providers and individual circumstances.
Pingback: Credit Card Utilisation Explained (And Why It Matters in the UK) - BudgetKin
Pingback: Credit Card Mistakes That Hurt Your Credit Score in the UK - BudgetKin